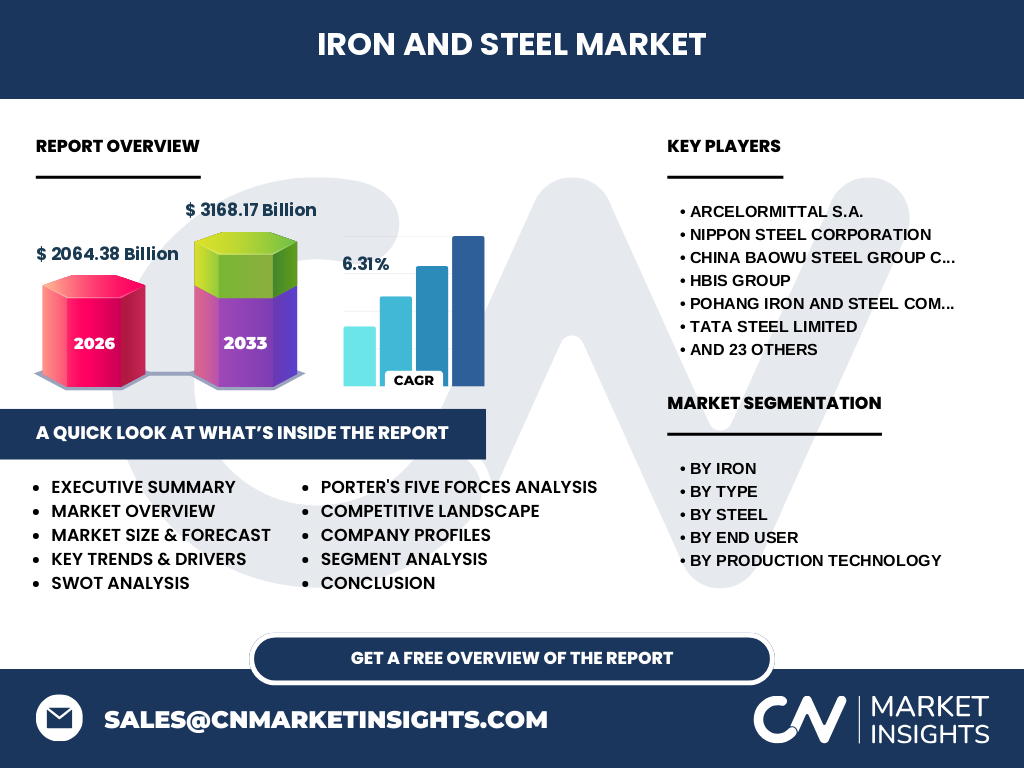
Market overview of the Iron And Steel Market
Our analysis indicates the Iron And Steel Market anchors global industrial manufacturing, scaling to USD 2064.38 Billion in 2026. This foundational sector supplies critical raw inputs for infrastructure, mobility, and heavy machinery, governed by stringent regulatory frameworks from bodies like the World Steel Association.
Key market drivers, restraints, challenges, and opportunities shaping Iron And Steel Market
Urbanization and decarbonization pressures define the Iron And Steel Market industry trends. While high capital expenditures and carbon tax restraints challenge traditional blast furnaces, rising Electric Arc Furnace adoption opens lucrative avenues for green steel production.
Emerging trends and growth patterns in Iron And Steel Market
The shift toward hydrogen-based direct reduction and scrap-based Electric Arc Furnace technology is revolutionizing the Iron And Steel Market. Producers increasingly prioritize low-carbon footprints to comply with EU CBAM regulations.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain fractures severely bottlenecked coking coal and iron ore logistics across major ports like Shanghai and Rotterdam. However, robust fiscal stimulus packages fueled a V-shaped recovery in infrastructure demand.
Competitive benchmarking and strategic dynamics
Market consolidation is led by giants like ArcelorMittal S.A., China BaoWu Steel Group Corporation Limited, and Nippon Steel Corporation. These players leverage vertical integration and regional acquisitions to mitigate raw material volatility.
Executive summary of key findings
Valued at USD 2064.38 Billion in 2026, the Iron And Steel Market is poised for substantial expansion, driven by technological evolution and surging demand from the building and automotive sectors.
Market forecast for the Iron And Steel Market from 2027 to 2033
Projections show the Iron And Steel Market expanding from 2027 to 2033 to reach USD 3168.17 Billion, expanding at a robust 6.31% CAGR driven by emerging economies.
Segmentation analysis across product lines and end-users
The market segments by iron (Pig Iron, Cast Iron, Wrought Iron, Ductile Iron), type (Iron, Steel), steel grades (Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel), end-users, and production technology like Basic Oxygen Furnace and Electric Arc Furnace.
Geographic distribution and regional performance
Asia-Pacific dominates the Iron And Steel Market market size, propelled by massive construction activities in China and India, whereas North America and Europe focus on high-value alloy and stainless steel applications.
In-depth regional review of high-growth territories
Rapid industrialization across developing Asian economies creates localized supply deficits, compelling regional mills to expand capacity. Meanwhile, European producers navigate stringent carbon pricing mechanisms that penalize traditional blast furnace outputs.
Company profiles and strategic positioning
Industry leaders such as Tata Steel Limited, Nucor Corporation, and POSCO Holdings Inc. deploy distinct strategies, balancing low-cost mass production with specialty alloy development for aerospace and automotive sectors.
Porter's Five Forces analysis of the sector
Bargaining power of raw material suppliers remains moderate to high for iron ore and coking coal miners, while competitive rivalry is intense among established global conglomerates holding excess capacity.
SWOT analysis of the global landscape
Strengths lie in established supply chains; weaknesses involve high carbon intensity. Opportunities abound in green hydrogen reduction, while geopolitical trade tariffs pose persistent external threats.
Value chain analysis from raw inputs to end-users
The value chain flows from iron ore mining and coking coal extraction through primary smelting via Basic Oxygen Furnace or Electric Arc Furnace routes, culminating in fabricated products for automotive and construction end-users.
Investment insights and high-potential areas
Investors should target green steel initiatives, scrap recycling infrastructure, and high-margin specialty alloy producers capable of meeting stringent automotive lightweighting requirements.
Conclusion and core takeaways
The Iron And Steel Market presents lucrative opportunities backed by a 6.31% CAGR through 2033, heavily favoring innovators who successfully decarbonize production processes.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated by combining trade registry data from the World Steel Association, primary executive stakeholder interviews, and macroeconomic industrial output indicators.
Scope of the report and coverage parameters
This report covers global demand trends, production technology splits, and regional forecasts from 2026 to 2033, excluding localized informal scrap collection economies.
Recent developments, M&A, and strategic moves
Recent market activity highlights major acquisitions and joint ventures focused on carbon capture integration, green hydrogen pilots, and supply chain localization by firms like JFE Steel Corporation and Gerdau S.A.